


Global markets watch Q3

Matt Brennan, Scottish Widows Head of Asset Allocation & Market Insights, shares his latest views on the shorter-term outlook for equities and bonds, and the opportunities and risks investors should be watching out for.
We also provide a clear, at-a-glance view of our longer-term rating for key markets from very negative through to very positive over the next 3 years and longer.
Equities
Short-term outlook: Globally, equities achieved another step higher in the third quarter, helped by buoyancy in value-related sectors. Despite this, global equity market concentration remains an issue, given the heavy skew towards US technology giants. Against a backdrop of relatively full valuations, market concentration, monetary policy uncertainty and the potential for further geopolitical instability, we believe volatility could return in the near term. In our view, it is important to have a spread of geographical equity market exposure, and while equities remain the mainstay of our long-term growth exposure, it is relatively less attractive than fixed income going forward.
Long-term view:
UK equities
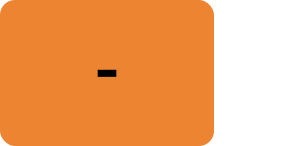
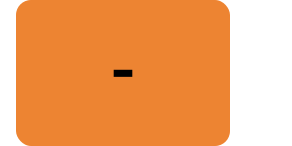
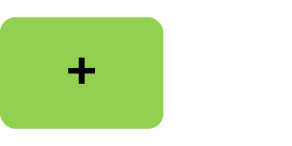
Short-term outlook: The UK equity market’s limited exposure to the technology sector has been a factor holding it back in recent years. Despite robust year-to-date gains, the market has trailed the rise in global equities. As value has returned to favour in the third quarter, the UK has slightly outpaced the rise in global equities, helped by the domestic revenue focus of UK mid-caps. Valuation, sectoral spread and diverse global revenue exposures all add to our relatively positive long-term view.
Long-term view:
Long-term view:
US equities
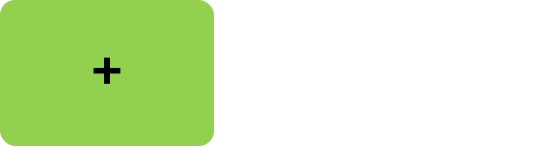
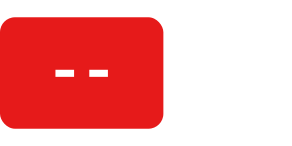
Short-term outlook: US equities remain fully valued with market leadership concentrated in growth-related sectors. Risks around AI companies’ substantial capital expenditure plans will be a dominant focus in the coming quarters. In the wake of September’s rate hike, inflation and interest rate changes may come back in focus later in the year. Further out, we believe diversification across other regions may prove beneficial as potential US returns could look relatively less attractive over the longer term.
Long-term view:
Long-term view:
Europe (ex-UK) equities
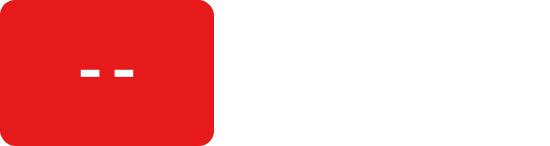
Short-term outlook: The European Central Bank has hiked rates twice this year amid inflation worries. Despite attractive valuation levels, Europe has sectoral exposure to geopolitical risk and muted shorter- and longer-term economic growth prospects.
Long-term view:
Long-term view:
Japanese equities
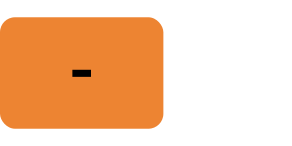
Short-term outlook: Over the near term, Japan could see its current earnings strength, and its distinct economic and market drivers offset by pressure from currency volatility and monetary policy normalisation. Over the long term, Japan’s structural reforms could help the market, but lower economic and corporate growth prospects are a likely negative offset.
Long-term view:
Long-term view:
Asia Pacific (ex-Japan) equities
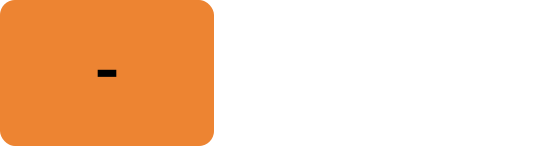
Short-term outlook: The market is slightly overvalued but that is broadly offset by potentially robust earnings growth over the longer term. Markets such as Australia, Hong Kong, Singapore and New Zealand still offer attractive income and remain appealing exposures in the region and as part of a diversified global equity exposure.
Long-term view:
Long-term view:
Emerging Market equities
Short-term outlook: Valuations remain relatively attractive in our view, though we continue to monitor volatility within markets catering to strong demand in semiconductors and other AI-related hardware. Ongoing economic growth potential, demographic and structural tailwinds, including relatively lower debt burdens, make emerging markets attractive with a longer-term view.
Long-term view:
Long-term view:
Bonds
Short-term outlook: Recent market weakness across most areas of the bond market has continued to present opportunities and bolstered our constructive view of the longer-term prospects within fixed income as a whole. Income levels from good quality credit are particularly attractive. We believe in holding a diversified blend of government bonds and credit, in different geographies and with different characteristics, and which can continue to provide income-generation benefits.
Long-term view:
Government Bonds
Short-term outlook: Despite increasingly supportive real yields and potentially improved longer-term total returns, we prefer other areas of fixed income. Yields have risen over the last quarter because of fears around inflation, government debt worries, and heavy issuance, for example. Overall, within the asset class, we prefer having a mix of government bonds, with a slight skew towards UK gilts.
Long-term view:
Long-term view:
Investment Grade Corporate Bonds
Short-term outlook: The third quarter saw yields rise in investment grade credit. As well as inflation fears, the huge AI-related expansion, which includes the datacentre buildout, has led to heavy issuance competition. This volatility could continue over the near term. However, on a long-term view, we think investment grade can still provide attractive income and could outperform government debt. Within this, we broadly favour a skew to sterling corporate bonds over global peers.
Long-term view:
Long-term view:
Global High Yield Bonds
Short-term outlook: In recent months, high yield weakened but outpaced investment grade and government bonds. Its further outperformance within the asset class could limit its near-term potential amid possible ongoing market volatility. Further out, high yield has generally lower interest rate sensitivity and has income attractions.
Long-term view:
Long-term view:
Emerging Market Debt
Short-term outlook: Near-term yield attractions remain intact against a backdrop of weakness in the third quarter. Longer term, the asset class is supported by structural growth, diversification benefits and potentially favourable currency trends. We prefer broad exposure to both US-dollar and local-currency emerging market debt. We will continue monitoring the idiosyncratic risk potential.
Long-term view:
Long-term view:
Alternatives
Short-term outlook: We believe alternatives have an important role to play in multi-asset portfolios, providing an opportunity to invest in assets with returns that have lower correlations to equities and bonds. Attractions include assets with inflation protection, income benefits and capital growth potential.
Long-term view:
Global Listed Property
Short-term outlook: The main benefits of listed property – such as real-estate investment trusts – are the high dividend yield that has some inflation linkage and diversified property market exposure. The segment is currently supported by relatively attractive valuations but tempered by the asset class’s interest rate sensitivity in the current environment of tightening at some major central banks.
Long-term view:
Long-term view:
The long-term view ratings reflect our assessment of the attractiveness of different asset classes over a three-year plus investment horizon. They provide a broad framework for investment decision-making and should not be viewed as the current positioning of any specific fund, portfolio or investment proposition.


